

Wall Street is slow to identify businesses that thrive in parts of the market it doesn’t observe directly. Here’s the reality: the markets and big banks are run by wealthy middle-aged men that have a specific lens of the world. I’ve worked in different faucets of finance and this has also been my personal experience over the years.
Don’t misunderstand me — I am not complaining about this. Instead, I’ve noticed that this provides an opportunity for folks that are observant. Wall Street and the market are slow to react to:
Products bought mostly by women and minorities. When I say minorities, I don’t only mean of race. I also mean diversity of income level.
Businesses that have customers in regions outside of major cities.
It’s a structural gap in the market and it’s a persistent theme over the last 30 years. I’m just a dude that sits at my computer 14 hours a day researching the market. Even with that kind of effort, I cannot realistically out-research a Goldman analyst on AI companies. I simply don’t have the resources, reach, and access.
HOWEVER, we have a specific power as retail investors that Wall Street doesn’t have. This would be the power of observation outside of the metropolitan bubble. I believe I’ve identified 3 different companies with large upside growth potential, supported by fundamental analysis of the latest earnings and long-term trends.
Interestingly, two positions have outperformed against the S&P 500 over the last twelve months, despite being uncorrelated to technology. One of the positions have underperformed but this provides us with any opportunity to accumulate. We can refer to the performance on the chart below.

I’ll cover all three of these businesses and their recent strength. I’ve provide some commentary on the first stock for free because I believe that it’s a business you’ve almost certainly bought from. If you want to stay updated on my articles, please subscribe so you don’t miss anything.
👉 Gift an annual subscription and receive a YEAR of paid access for free!
The Data Doesn’t Explain The Why
When Wall Street builds a forward-looking thesis, they generally analyze data that supports consumer metrics. This includes analyzing data like credit card spending, app downloads, foot traffic in the markets they specifically sample.
Having been an analyst myself, I use a lot of the same data for my own research. However, there’s a caveat to this style of analytics.
The data doesn’t actually explain why people are spending or consuming the way that they are. For instance, the data can’t determine why someone will buy a $350 air fryer over a $120 traditional toaster oven. The data doesn’t explain why spending happens the way that it does. Typically, the data only estimates at which pace the spending will accelerate or decelerate and what catalysts will influence those changes.
You’ll see analysts issue reports on a similar group of companies because the data is generally skewed towards a specific sector. That’s why there’s such an abundance of reports on different technology and AI companies.
The silver lining is that there’s only a small window of time before Wall Street eventually sees the value that you do. This is exactly the period you want to start accumulating a stock. When it is out of favor or out of the spotlight, this is when the riches can be built.
That’s legit what’s happening with META 0.00%↑ and UBER 0.00%↑ right now. Everyone is focused on these other AI businesses and now the potential risks have taken over the narrative. As a result, both of these companies are on massive sales and I’ve been accumulating shares.


Stock #1: SharkNinja (SN)
While it isn’t exclusive to women, the data clearly supports that women are the main consumer of things like Air fryers, robot vacuums, multi-cookers, blenders, coffee systems, hair tools, across more than 36 household sub-categories that SharkNinja SN 0.00%↑ services .
I bet you regularly use an Airfryer now instead of your oven.
I bet you have a nice coffee maker in your house.
I bet you have some sort of air purifier.
Perhaps you have a robo-vacuum.

SN 0.00%↑ recently reported its Q2 earnings for 2026 and the results were solid. Net sales for the business were strong and landed at $1.77B. The business operates across tons of different segments and this represents an increase of 22.2% year over year and is the fastest growth rate since 2024.
International sales jumped 36.6% as well, which means that SN is growing its revenue globally, not only in the U.S. Additionally, the Cooking and beverage segment grew 36.5%. This represents the thirteenth consecutive quarter of double digit sales growth for the company.
Management is so confident in their outlook that they raised full year guidance to 16% to 17% sales growth. Double digit revenue growth will likely be accompanied by double-digit earnings per share growth.
Interestingly, SN also collected a $247.1M tariff refund, which admittedly inflated earnings by a bit. However, this was offset by the fact that management bought back $100 million of stock in the quarter. Management will only buy back its own stock for one reason: they think it will continue to go up!
In the performance chart I originally provided, SN was the stock that outperformed the S&P500 with a wide margin. I believe this outperformance can continue over the next twelve months.
SharkNinja also has incredible profitability metrics, as we can see below:

Here’s the kicker, the company only sits at a market cap of $26B. I believe this is a $80B+ market cap company just through the brand loyalty alone. Brand loyalty is strong with SharkNinja and I’d argue that it carries the same appeal that Apple AAPL 0.00%↑ does with smartphones. If you buy a SharkNinja airfyer, it become hard to buy any other brand after that.

Stock #2…
Farmer Mac (AGM)
Farmer Mac AGM 0.00%↑ buys loans from rural lenders so those lenders can keep lending. Think of AGM as the rural version of what Fannie Mae does for housing. AGM operates in a very niche area of the market and that’s why the business isn’t well-known. Despite this, farm is huge.
I doubt any of you have heard of this company, which drives the point home further.
I previously initiated a position in AGM at $93 per share. I’ve held since 2022 and remained patient, simply collecting a dividend along the way. With that said, I have fully exited the position and taken that gain. HOWEVER, I still believe that the stock is likely to trend higher, especially because of the strength of the last earnings report.
Q2 earnings were reported om July 30th. Core earnings hit a record $58.8 million, or $5.40 per diluted share, up 24% year over year. Diluted EPS $5.41, up 21%.
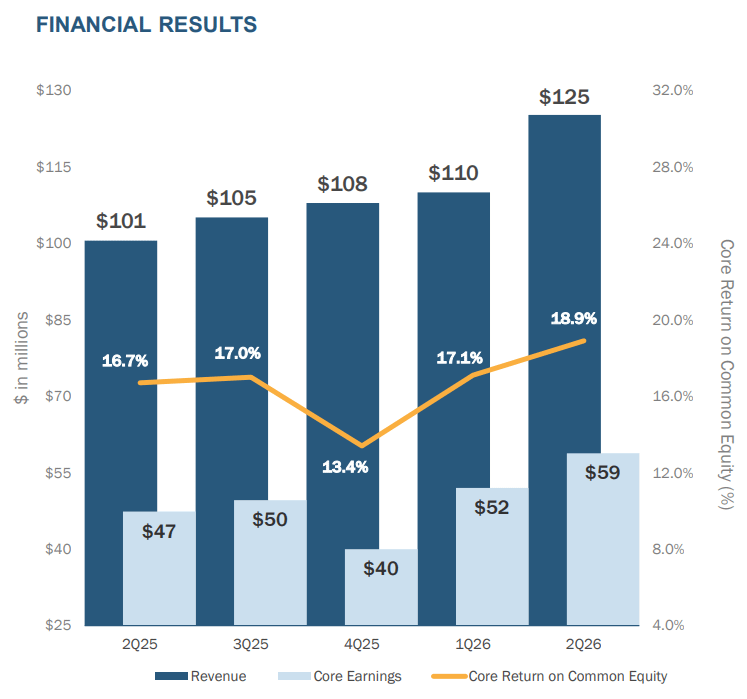
AGM’s business volume reached $37.2 billion, which is up 22% from the prior year. Net interest income rose 22% to $118.1M for the quarter as well. Farm and Ranch volume grew 21% to $22.0 billion year-over-year.
AGM declared a quarterly dividend of $1.60 per quarter. This means that AGM now offers a dividend yield of about 3.5%. The dividend was raised 14 consecutive years, payout ratio still in the low thirties.
Interestingly, AGM only has 212 employees so I don’t think it makes enough noise to land on any major radars for investors. I believe this tells you how little attention this company gets relative to what it does.
AGM thrives in regions of the U.S. where most of the population don’t live. This means that the wealthiest investors aren’t even thinking about a business like AGM and this is where us retail investors have an edge.
Stock#3: DoorDash (DASH)
I put this on my list because of the suburban and rural piece. Consumer habits are changing and I believe that delivery is the next step.
We’ve gone through the drivethru era.
We’ve gone through the sit-in restaurant era.
And now I think that food delivery is the next progression of that. This is where DoorDash DASH 0.00%↑ would come in and service the market.
DoorDash is one of the most watched companies in technology yet it still has a market cap that sits under $100B. It is covered constantly, discussed constantly, yet it isn’t priced accurately.
Based on the latest earnings report, I believe that growth is going to accelerate going forward.
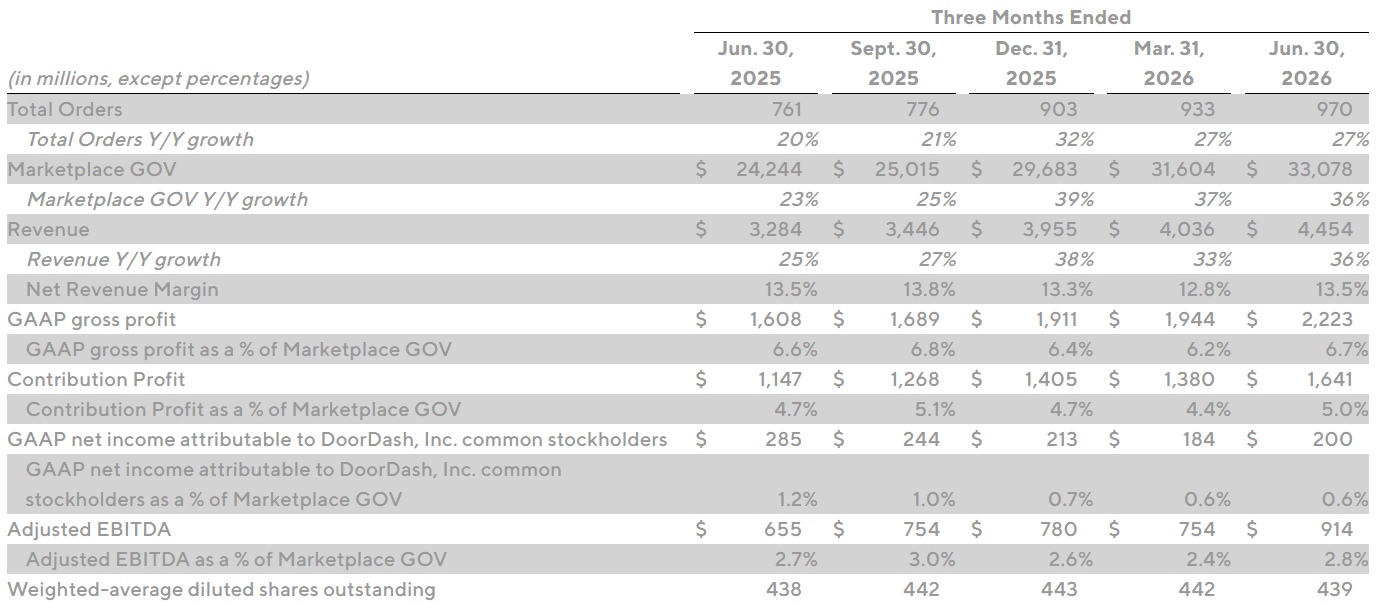
Here are the highlights from the last earnings:
DASH’s revenue rose 36%, amount to $4.45B for the quarter.
Total orders volume grew 27% to 970 million, which means that more people are placing orders for their food to get delivered.
Marketplace gross order value climbed 36% to $33.1 billion.
Monthly active users hit a record as well and I think this will continue to climb as the business prioritizes its subscription model, ‘DashPass’. DashPass added more subscribers over the past year than in the prior two years combined. As more people start to pay a monthly subscription for exclusive perks, DASH slowly secures more long-term sustainable revenue.
Lastly, Merchant services grew 40% across more than 150,000 businesses, indicating that more businesses are utilizing DASH’s service and represents another revenue stream for the business.
I personally believe that verticals like grocery are on a path to gross profit positivity by year end. Times are changing and younger people are okay with paying a premium for the convenience.
Positioning
For full disclosure, I haven’t initiated a position in any of these stocks yet. Of these three, I am most likely to add to SharkNinja and DoorDash. For both of these, I am waiting for a sizeable pullback to add a lump sum.
I love DASH!
I wish we had learned about AGM before the jump up last month. SN jumped up last month too! 🤩